By Raymond Nash

Business Planning

Altering Existing Buy/Sell Arrangements

During the month of July, we are focusing on business planning in the wake of the Supreme Court ruling in Connelly v. U.S. On June 6, 2024, the U.S. Supreme Court affirmed the 8th U.S. Circuit Court of Appeals’ decision in Connelly v. U.S. This ruling determines that the value of the business at a shareholder’s death will be increased by any life insurance proceeds that are received without an offsetting reduction for the amount of the stock redemption liability.

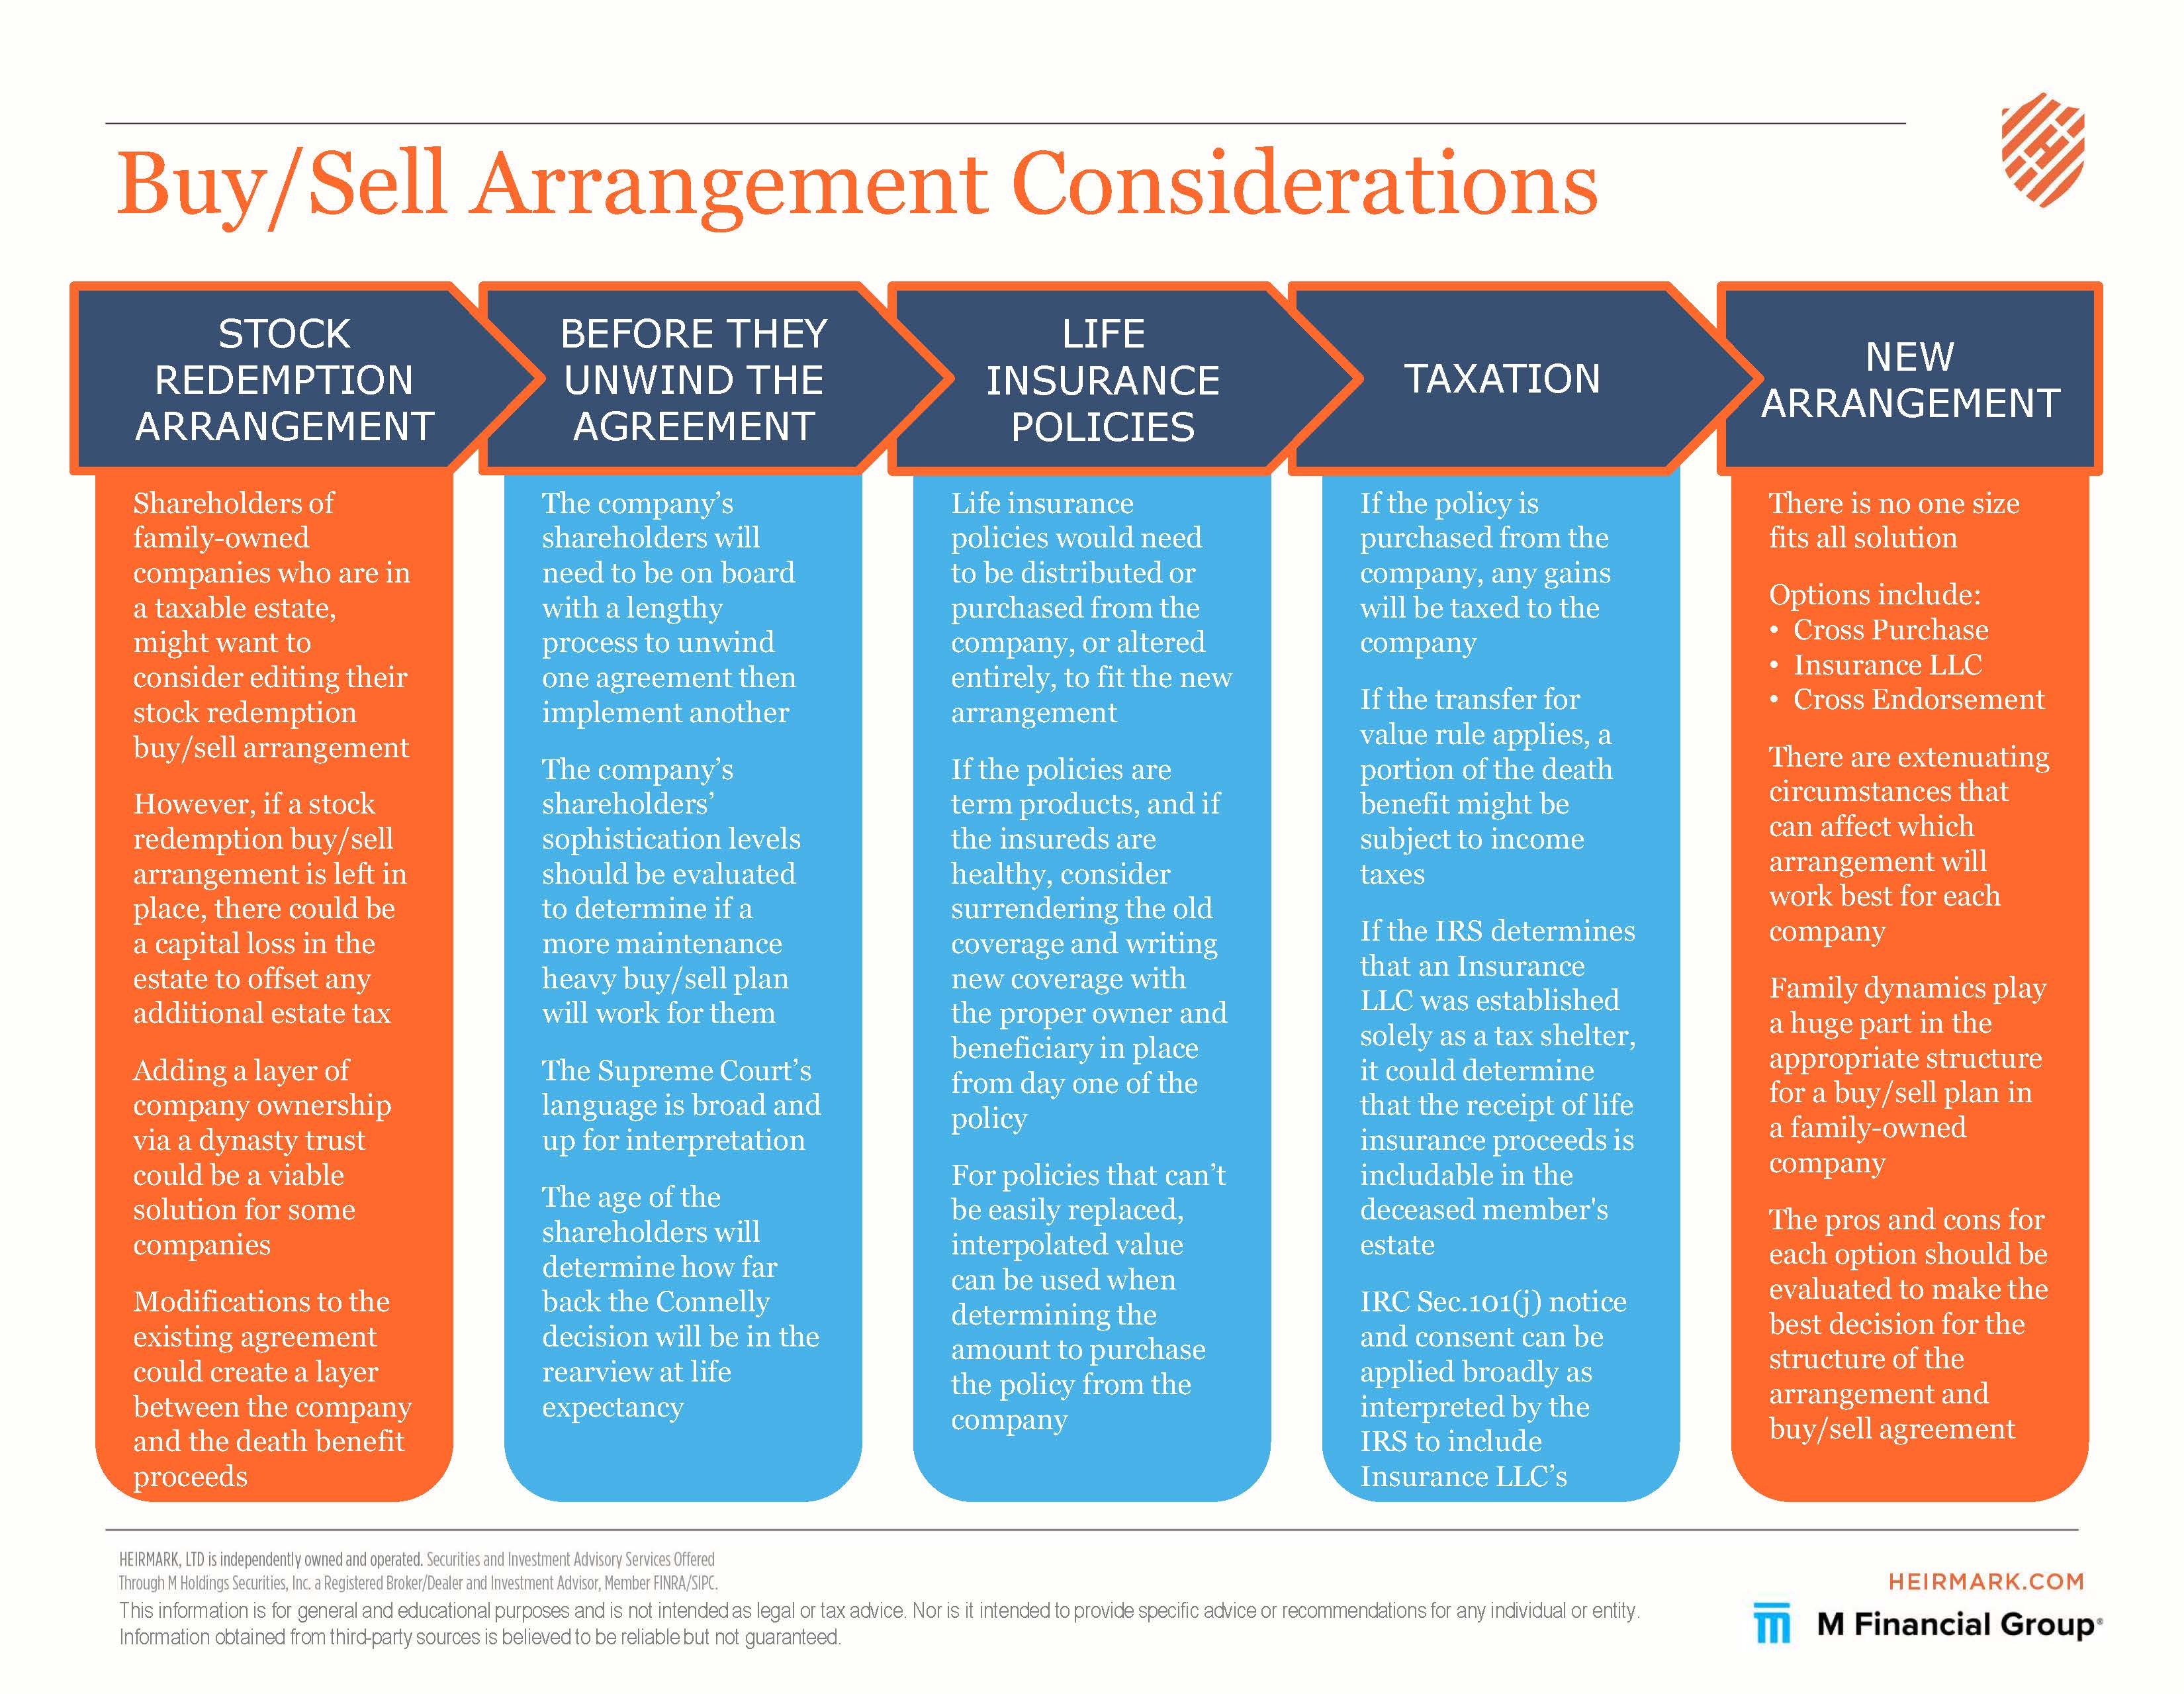
The unprecedented Connelly U.S. Supreme Court decision has certainly left behind more questions than answers about how to properly structure a buy/sell agreement.  While a kneejerk reaction is tempting, it’s important to acknowledge that not every company will necessarily need to re-hash their existing stock redemption buy/sell agreement.  This ruling mainly affects family-owned companies with shareholders who have an estate that exceeds the exemption limit (either now or after the presumed sunset in 2026).  Of those family-owned companies, we expect to see some that will not move from their existing stock redemption buy/sell agreements, since they feel they meet the parameters outlined in IRC Sec. 2703.

Additionally, there is some discussion around the potential capital loss in the estate to offset (when spread out over multiple years) some of the additional estate tax.  For Connelly, the estate redeemed its shares at $3M but the IRS determined that the shares should have been worth $5.29M, creating a capital loss of $2.29M.  Though it is likely impossible to apply the full amount in a lifetime, this capital loss might be available for use by the heir(s) in future years to offset other income.  Of course, the structure of the company and individual situations will be determining factors when calculating any capital loss for each shareholder’s heir(s).  If the estate tax liability is small enough, offsetting it with a capital loss might be a solution that each shareholder and their family are willing to consider.

Another solution to explore before moving away from an existing stock redemption arrangement is using a trust to own a family-owned company.  In theory, the shareholders would execute a dynasty trust to own the company, any life insurance policies would still be owned by the company, and the company would be the beneficiary, so there would be no transfer for value.  Then the life insurance proceeds would be paid to the trust and wouldn’t increase the deceased shareholder’s business equity for estate tax calculations.  The death benefit proceeds would be paid to the deceased shareholder’s heir(s) from the trust.  Minimal changes would need to be made to the buy/sell agreement, but there would be additional trust taxation and maintenance considerations when determining if this solution is right for a company.

Alternatively, shareholders can fund the existing stock redemption buy/sell agreement via contributions or loans.  Minimal changes to the agreement might be necessary, and any existing company-owned life insurance would need to be distributed to or purchased by the shareholders from the company, which could trigger transfer for value in companies that are not structured as partnerships.  After one shareholder dies, the other shareholders would receive the death benefit from the life insurance and either loan it or make a capital contribution to the company.  However, there is no guarantee that the remaining shareholders will honor this approach after a shareholder dies, and there is a chance they might seek to renegotiate the terms.  Additionally, if a loan is used, it would need ongoing maintenance.

Another possible approach to the existing stock redemption buy/sell agreement is to make minor modifications to change the structure of the arrangement.  For example, changing the agreement so the business has the first option to redeem, followed by the shareholders’ option to purchase can make the move to cross purchase life insurance a possibility without completely overhauling the whole agreement.  At the very least, a defined value clause should be added to every buy/sell agreement to outline the formula that determines the fair market value of the company.  This formula should be appropriate to the company’s industry and as specific as possible.

There is no one size fits all solution, so each company’s needs should be assessed and addressed individually.  As buy/sell agreements are reviewed and altered, we expect to see some areas where life insurance will need to be audited.  Contact us with any questions or opportunities to help you or your clients achieve identified goals. This is what we enjoy doing for only a select number of families, businesses, and charitable institutions each year, and we look forward to hearing from you.
Heirmark operates on a different model.

As a member of M Financial Group, we’re part of a select network of independent firms focused on advanced insurance planning for high-net-worth individuals and complex needs. This provides access to more customized structuring, deeper underwriting collaboration, and solutions not typically available through traditional channels—allowing us to approach each case with greater flexibility and design strategies around the client, not the product.

Heirmark is a premium life insurance advisory firm dedicated to helping affluent families, business owners, and their trusted advisors acquire custom-designed life insurance solutions that protect assets and preserve legacies.

Cleveland Office

PS Executives Center, Crown Centre, 5005 Rockside Road, Suite 600, Cleveland, OH 44131

Office of Supervisory Jurisdiction

1125 NW Couch Street, Suite 900, Portland, OR 97209

Copyright © 2026 HEIRMARK, LTD All Rights Reserved.

Securities and Investment advisory services offered through M Holdings Securities, Inc., a registered broker/dealer and investment advisor, member FINRA/SIPC. HEIRMARK, LTD is independently owned and operated. HEIRMARK, LTD is a member of M Financial Group. Please go to mfin.com/DisclosureStatement for further details regarding this relationship.


For important information related to M Securities, refer to the M Securities’ Client Relationship
Summary (Form CRS) by navigating to https://mfin.com/m-securities.


Check the background of this Firm and/or investment professional on FINRA's BrokerCheck.


Registered representatives are registered to conduct securities business and licensed to conduct insurance business in limited states.  Response to, or contact with, residents of other states will only be made upon compliance with applicable licensing and registration requirements.  The information in this website is for U.S. residents only and does not constitute an offer to sell, or a solicitation of an offer to purchase brokerage services to persons outside of the United States.


This site is for information purposes and should not be construed as legal or tax advice and is not intended to replace the advice of a qualified attorney, financial or tax advisor or plan provider.


Raymond Nash CA License #0G32030

Raymond Nash AR License #7081134

Heirmark CA License #0K00803

5784256 

Heirmark operates on a different model.

As a member of M Financial Group, we’re part of a select network of independent firms focused on advanced insurance planning for high-net-worth individuals and complex needs. This provides access to more customized structuring, deeper underwriting collaboration, and solutions not typically available through traditional channels—allowing us to approach each case with greater flexibility and design strategies around the client, not the product.

Heirmark is a premium life insurance advisory firm dedicated to helping affluent families, business owners, and their trusted advisors acquire custom-designed life insurance solutions that protect assets and preserve legacies.

Cleveland Office

PS Executives Center, Crown Centre, 5005 Rockside Road, Suite 600, Cleveland, OH 44131

Office of Supervisory Jurisdiction

1125 NW Couch Street, Suite 900, Portland, OR 97209

Copyright © 2026 HEIRMARK, LTD All Rights Reserved.

Securities and Investment advisory services offered through M Holdings Securities, Inc., a registered broker/dealer and investment advisor, member FINRA/SIPC. HEIRMARK, LTD is independently owned and operated. HEIRMARK, LTD is a member of M Financial Group. Please go to mfin.com/DisclosureStatement for further details regarding this relationship.


For important information related to M Securities, refer to the M Securities’ Client Relationship
Summary (Form CRS) by navigating to https://mfin.com/m-securities.


Check the background of this Firm and/or investment professional on FINRA's BrokerCheck.


Registered representatives are registered to conduct securities business and licensed to conduct insurance business in limited states.  Response to, or contact with, residents of other states will only be made upon compliance with applicable licensing and registration requirements.  The information in this website is for U.S. residents only and does not constitute an offer to sell, or a solicitation of an offer to purchase brokerage services to persons outside of the United States.


This site is for information purposes and should not be construed as legal or tax advice and is not intended to replace the advice of a qualified attorney, financial or tax advisor or plan provider.


Raymond Nash CA License #0G32030

Raymond Nash AR License #7081134

Heirmark CA License #0K00803

5784256 

Heirmark operates on a different model.

As a member of M Financial Group, we’re part of a select network of independent firms focused on advanced insurance planning for high-net-worth individuals and complex needs. This provides access to more customized structuring, deeper underwriting collaboration, and solutions not typically available through traditional channels—allowing us to approach each case with greater flexibility and design strategies around the client, not the product.

Heirmark is a premium life insurance advisory firm dedicated to helping affluent families, business owners, and their trusted advisors acquire custom-designed life insurance solutions that protect assets and preserve legacies.

Cleveland Office

PS Executives Center, Crown Centre, 5005 Rockside Road, Suite 600, Cleveland, OH 44131

Office of Supervisory Jurisdiction

1125 NW Couch Street, Suite 900, Portland, OR 97209

Copyright © 2026 HEIRMARK, LTD All Rights Reserved.

Securities and Investment advisory services offered through M Holdings Securities, Inc., a registered broker/dealer and investment advisor, member FINRA/SIPC. HEIRMARK, LTD is independently owned and operated. HEIRMARK, LTD is a member of M Financial Group. Please go to mfin.com/DisclosureStatement for further details regarding this relationship.


For important information related to M Securities, refer to the M Securities’ Client Relationship
Summary (Form CRS) by navigating to https://mfin.com/m-securities.


Check the background of this Firm and/or investment professional on FINRA's BrokerCheck.


Registered representatives are registered to conduct securities business and licensed to conduct insurance business in limited states.  Response to, or contact with, residents of other states will only be made upon compliance with applicable licensing and registration requirements.  The information in this website is for U.S. residents only and does not constitute an offer to sell, or a solicitation of an offer to purchase brokerage services to persons outside of the United States.


This site is for information purposes and should not be construed as legal or tax advice and is not intended to replace the advice of a qualified attorney, financial or tax advisor or plan provider.


Raymond Nash CA License #0G32030

Raymond Nash AR License #7081134

Heirmark CA License #0K00803

5784256