By Raymond Nash
In the First Week of Planning, My Advisor Said to Me…
Exemptions Have an Expiry
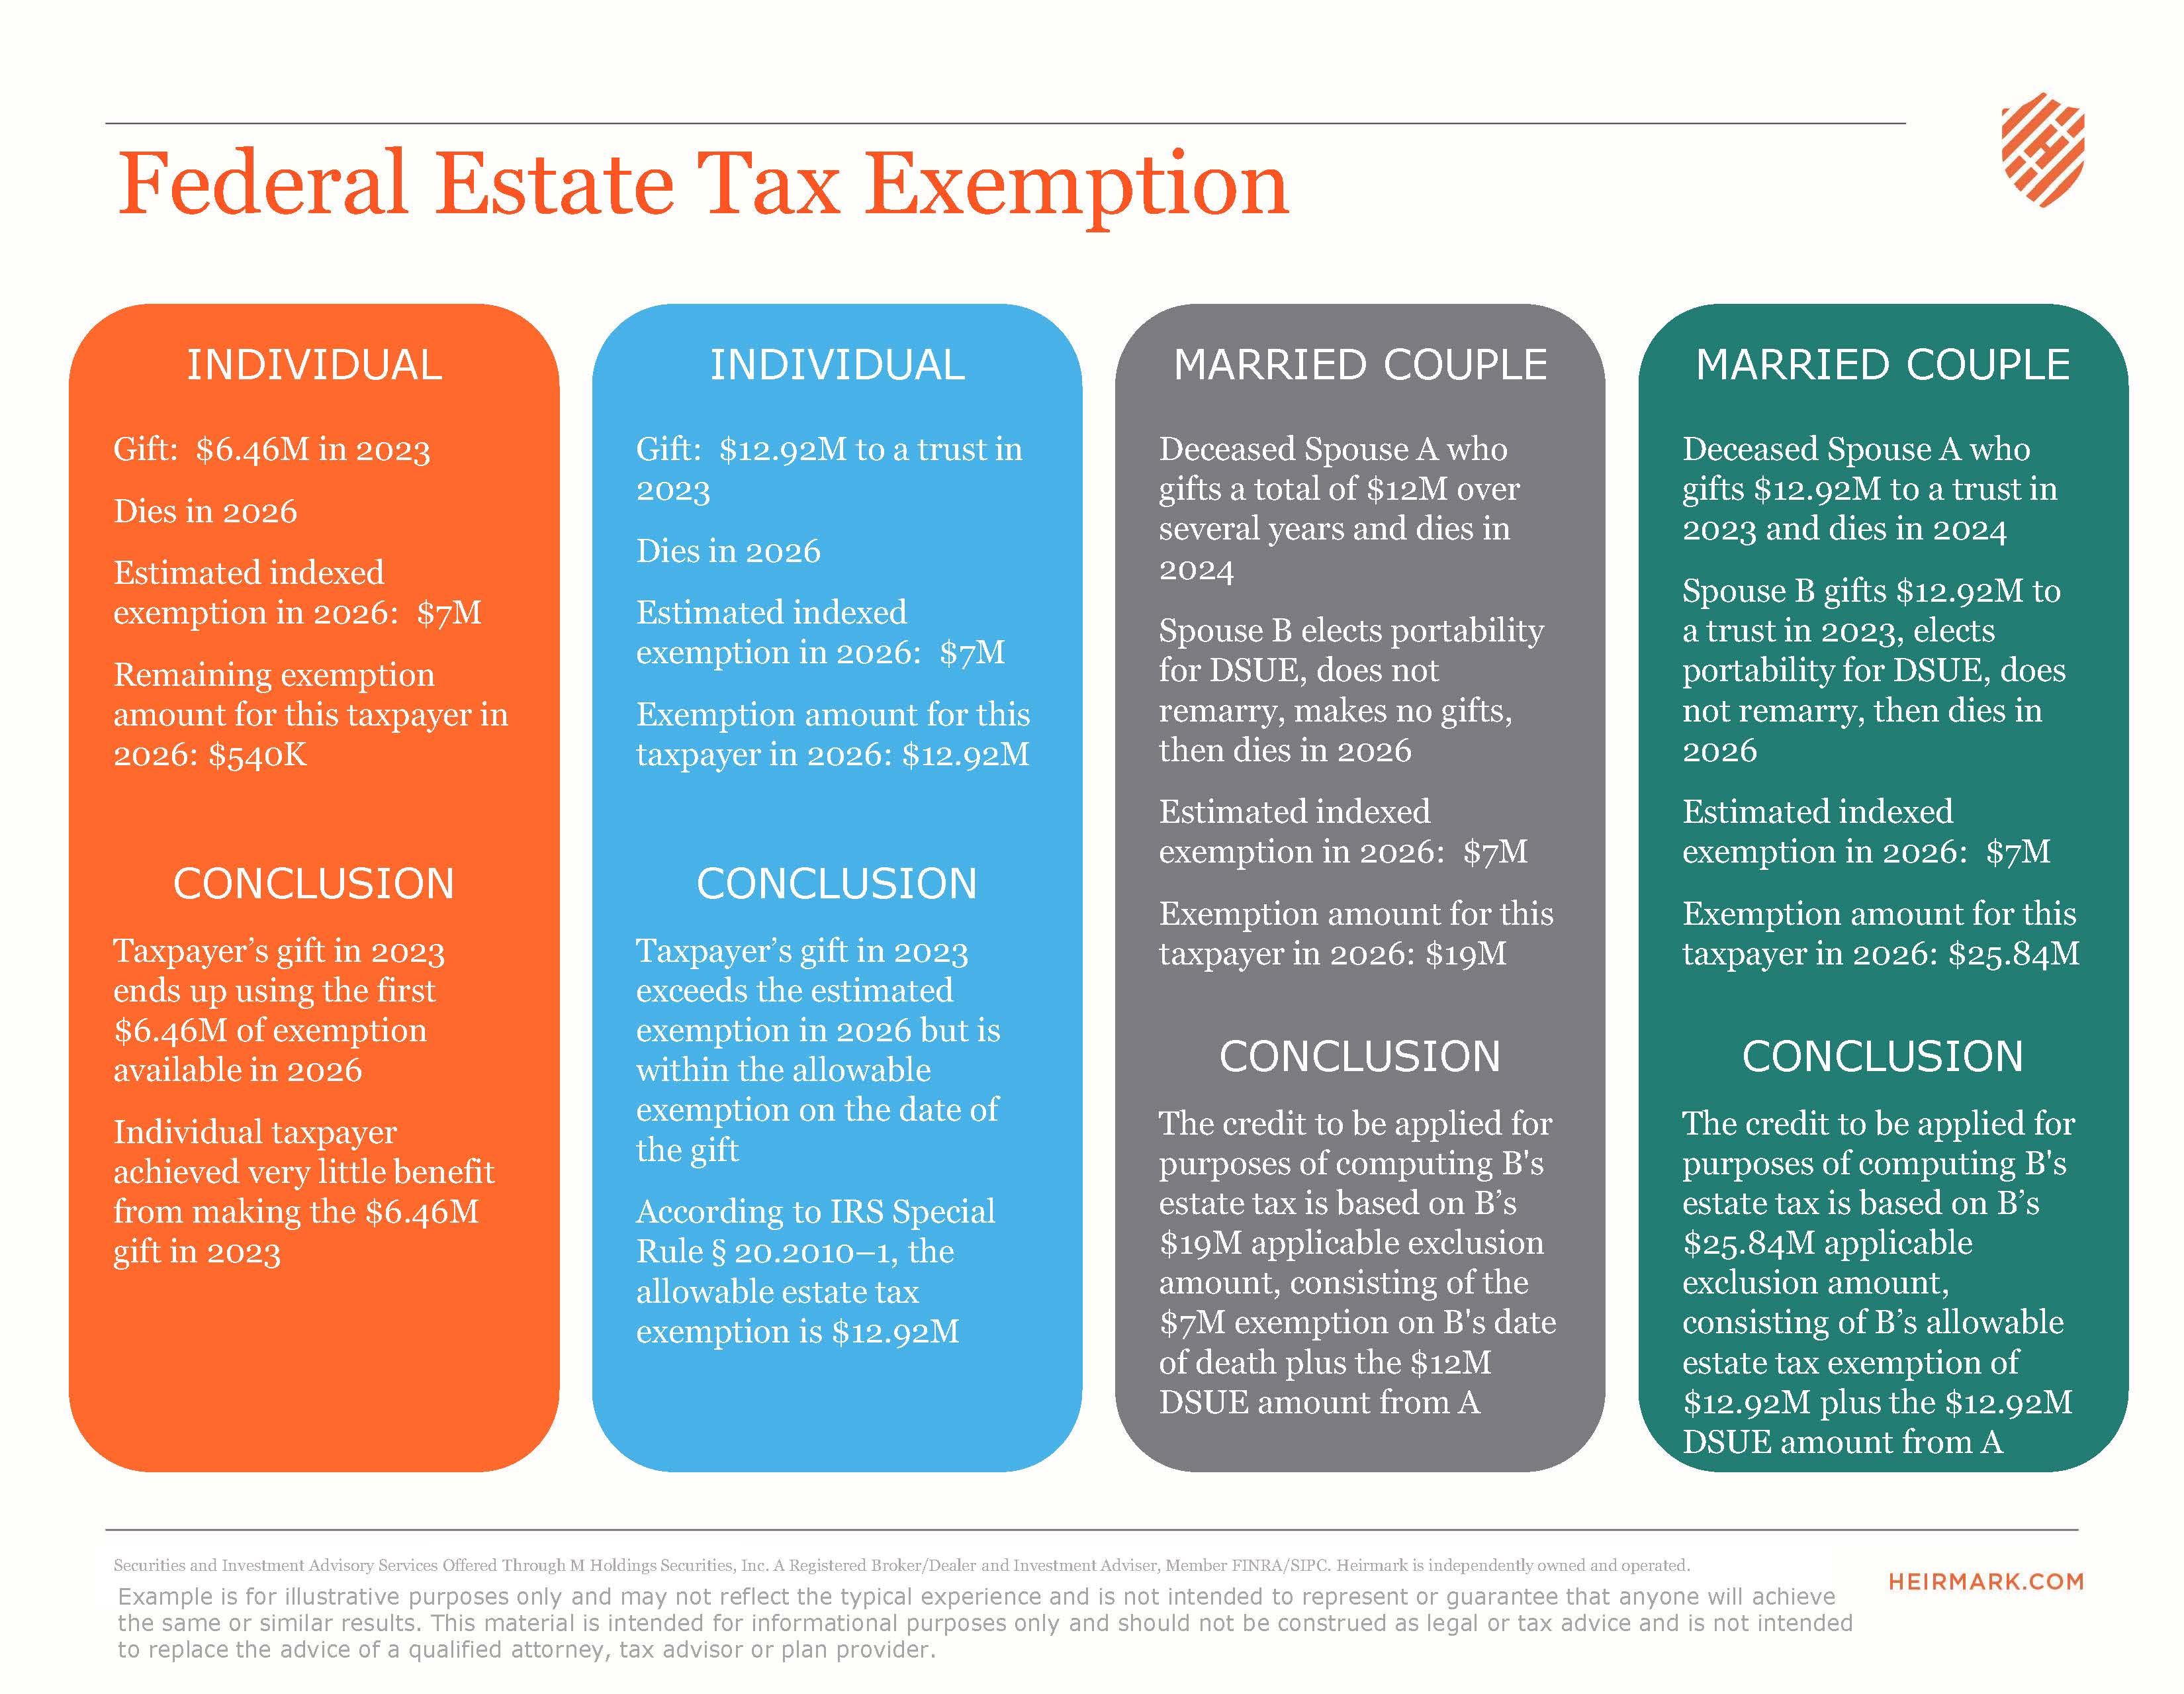
The Tax Cuts and Jobs Act (TCJA) of 2017 temporarily doubled the federal estate and gift tax exemption through the end of 2025. The individual exemption went from $5M to $10M (annually indexed for inflation). At the beginning of 2026, the temporarily doubling of the federal estate tax exemption is expected to expire and fall back to $5M (estimated at $6M-$7M when adjusted for inflation) for an individual and $10M (estimated at $12M-$14M when adjusted for inflation) for a married couple. Barring legislative action, the exemption will revert to pre-TCJA numbers and potentially expose many more estates to taxation at death.
The increased exemption as adjusted for inflation is a “use or lose” benefit and is available to a decedent who survives the increased exemption period only to the extent the decedent “used” it by making gifts during the increased exemption period. In order to use the temporarily doubled exemption without losing it, the entire remaining exemption amount must be gifted prior to 2026 (or prior to the legislation being repealed).
Contact us with any questions or opportunities to help your clients achieve their goals. This is what we enjoy doing for only a select number of families, businesses, and charitable institutions each year, and we look forward to hearing from you.