By Raymond Nash
Planning Your Legacy
Protecting Your Grandchildren
Most life insurance is not structured to benefit the insured. It’s implemented to benefit those who are left behind when the insured passes away. Leaving behind a significant death benefit can ease some of the difficulties of navigating a myriad of decisions, hurdles, and obstacles after an unexpected death. Whether benefiting your family, business, or favorite charity, the influx of funds at a difficult time can build a strong foundation for years to come.
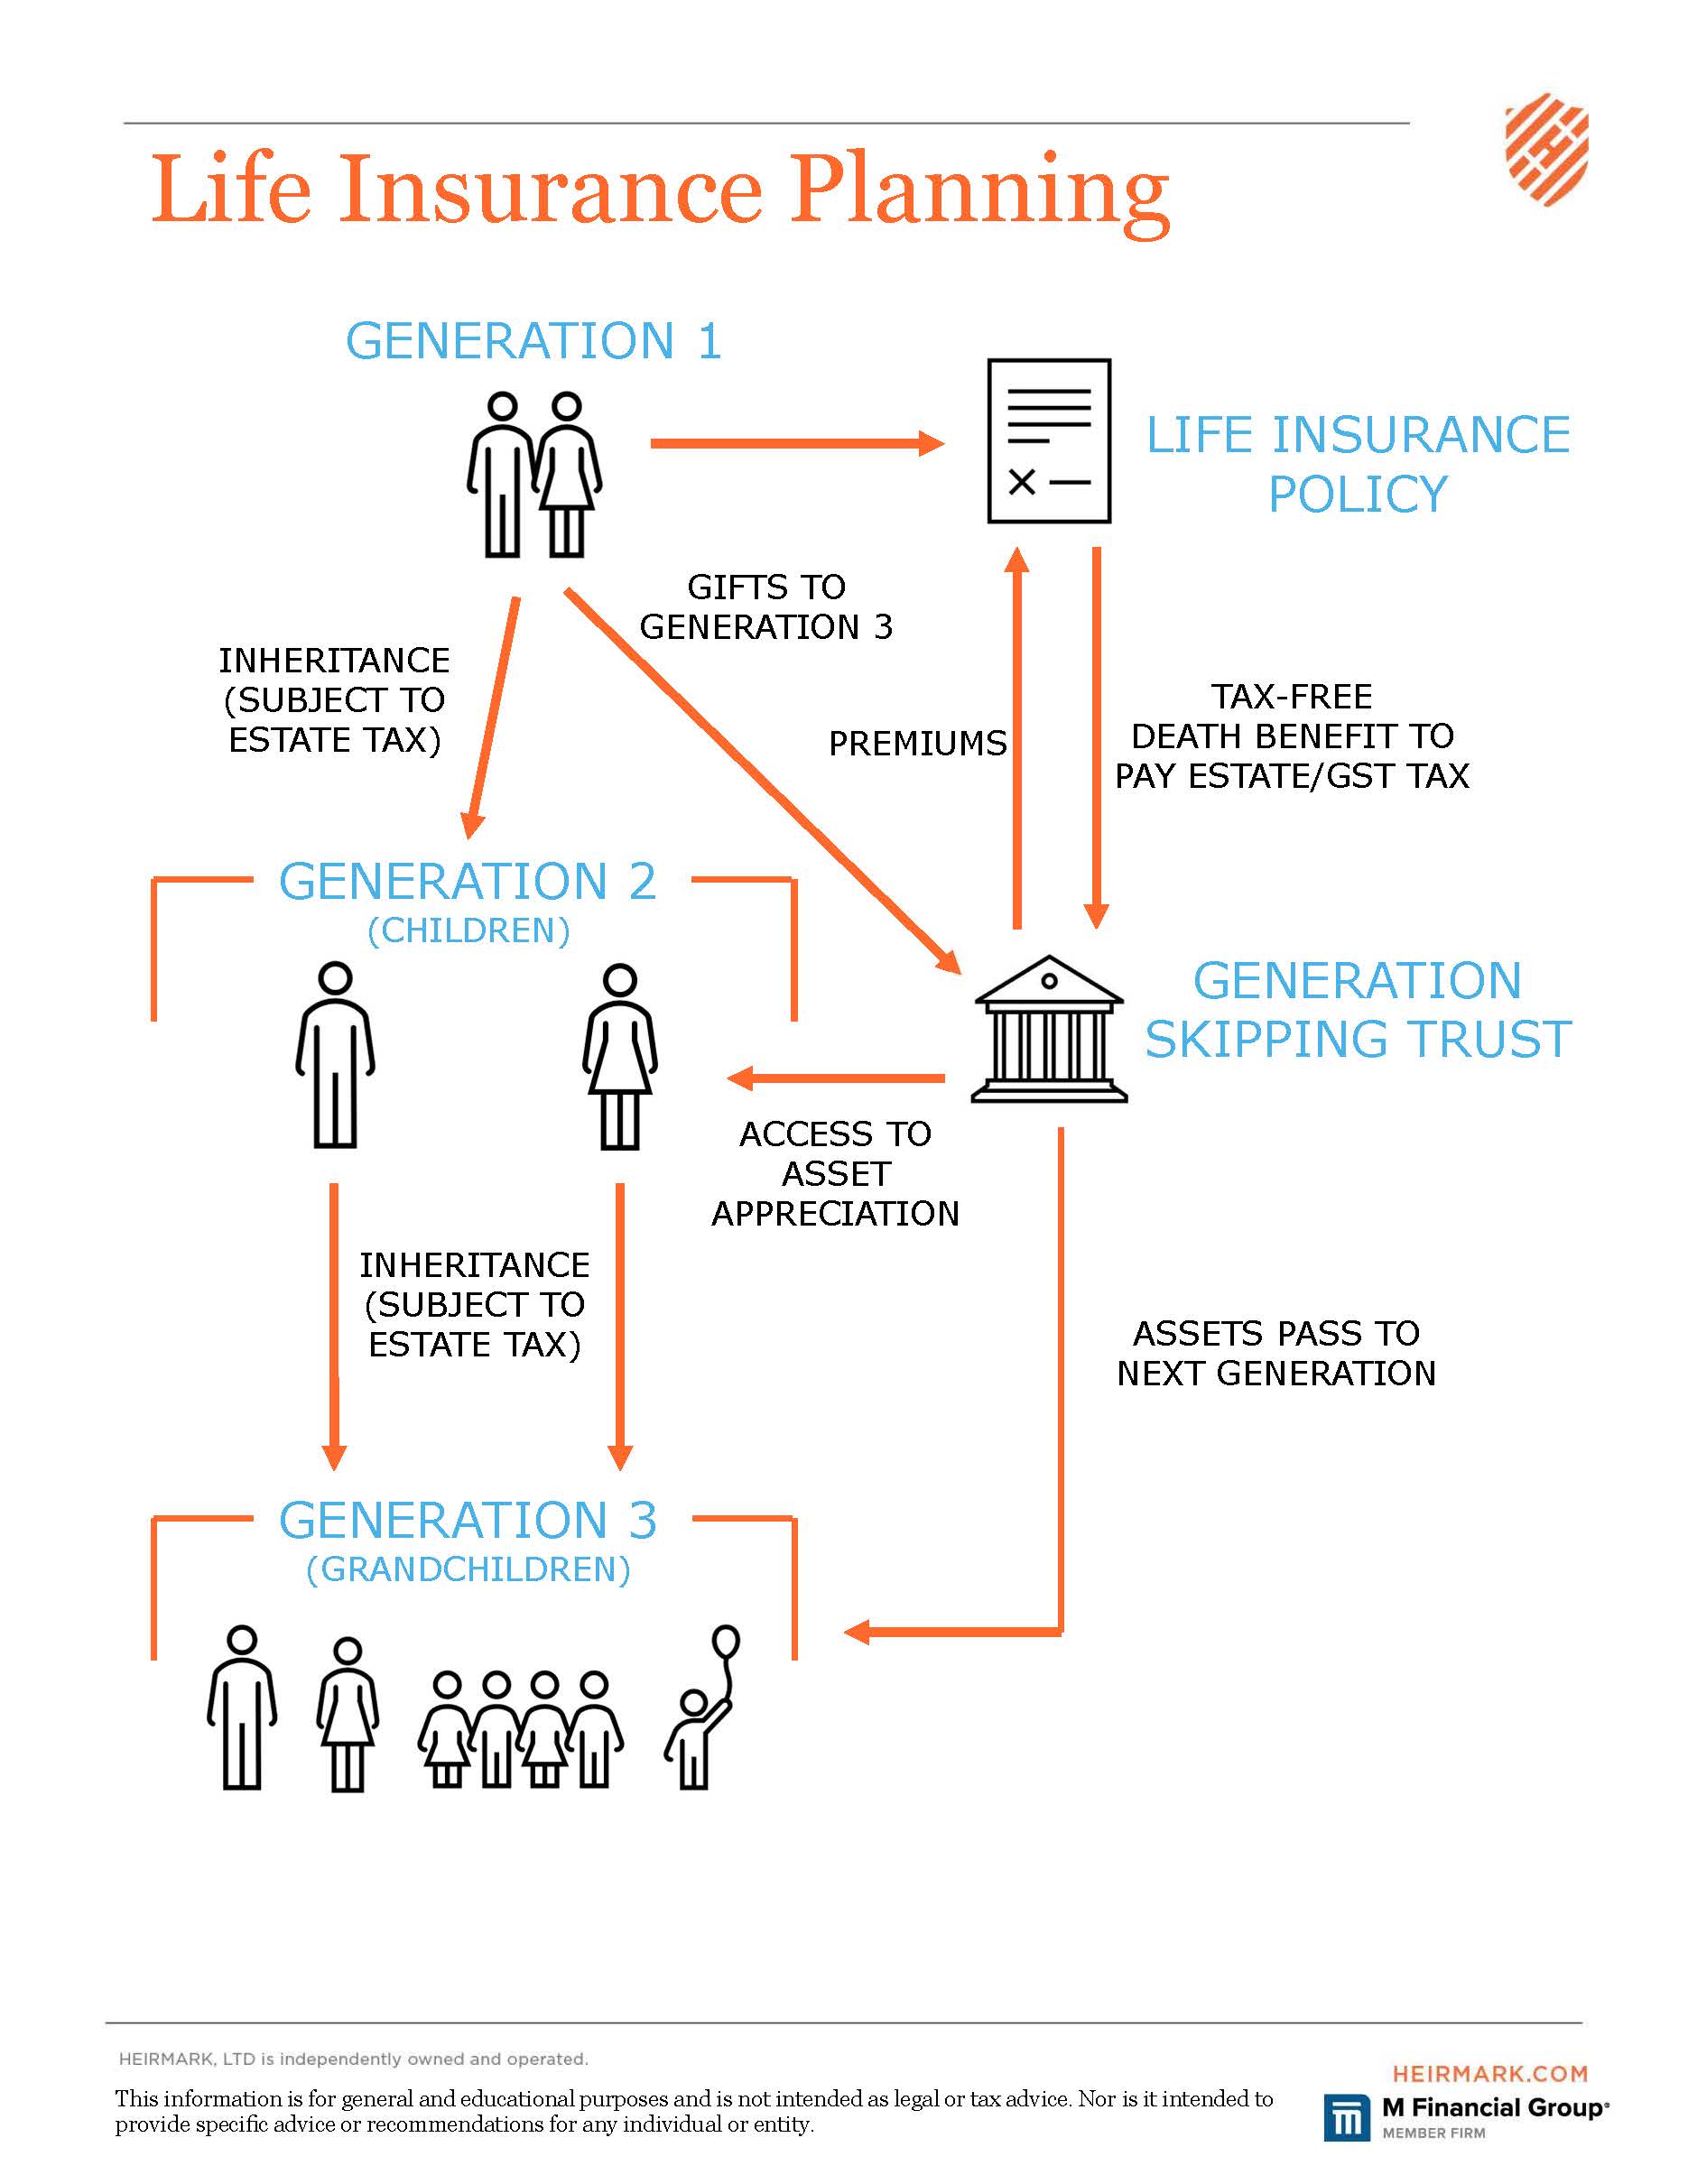
When considering the inheritance for grandchildren, it can be advantageous for ultra-affluent individuals to establish a Generation Skipping Trust (GST). A GST is a trust that is used to pass down wealth to anyone who is at least 37.5 years younger than the grantor. Typically used to pass wealth down to grandchildren, the trust can also be used to pass wealth to nieces/nephews or anyone else who meets the age requirement, whether related to the grantor or not.
By planning for a grandchild’s inheritance via a GST, the grantor can assure that the family’s wealth is preserved for at least two future generations. Additionally, gifting assets to future generations via a GST removes the assets from the taxable estate for the grantor’s children. Estate taxes and GST taxes will only be assessed when assets that exceed the exemption and exclusion amounts are distributed to the intended recipient (in our example, the grandchildren). The grantor can gift the lifetime exemption amount to the trust, in addition to the annual gift exclusion amount for each grandchild without incurring estate tax or GST tax. Any amount exceeding these limits might be subject to taxes. If the estate tax and GST tax are expected to incur, they can be offset with careful planning that includes a life insurance death benefit that is paid to the GST at the grantor’s death.
In addition to a GST for future generations (generation three and beyond), most affluent families make additional arrangements via trusts and life insurance policies for their children (generation two). However, there is no regulation to prevent generation two from accessing any appreciation on the assets held in a GST, as long as the original assets remain intact for the intended recipients. These terms can be outlined within the trust itself, along with stipulations for distributions to the future generation, such as limiting distributions to education expenses or determining planned periodic distributions instead of a lump sum amount. Creating liquidity inside the GST with help from a life insurance death benefit then setting boundaries around the use of the funds can help to preserve the family’s legacy for generations to come.
Contact us with any questions or opportunities to help you or your clients achieve identified goals. This is what we enjoy doing for only a select number of families, businesses, and charitable institutions each year, and we look forward to hearing from you.