By Raymond Nash
Business Planning
Looking Forward - Buy/Sell Arrangement Options
During the month of July, we are focusing on business planning in the wake of the Supreme Court ruling in Connelly v. U.S. On June 6, 2024, the U.S. Supreme Court affirmed the 8th U.S. Circuit Court of Appeals’ decision in Connelly v. U.S. This ruling determines that the value of the business at a shareholder’s death will be increased by any life insurance proceeds that are received without an offsetting reduction for the amount of the stock redemption liability.
When establishing a new buy/sell agreement for a company, the shareholders should consider the possible ramifications of the Supreme Court’s ruling when determining their preferred arrangement.
The first thing to consider is that this holding will not affect every business owner. Per Treas. Reg. 25.2703-1(b)(3), a company automatically meets the criteria for an exclusion if more than 50% is owned directly or indirectly by individuals who are not members of the same family. Additionally, if a business owner’s net worth, including their business equity and portion of any death benefit payable upon their mortality, falls below the projected estate tax exemption threshold, they might not incur any estate taxes. Of course, the unpredictability of where the estate tax exemption could lie in the coming years is another consideration altogether.
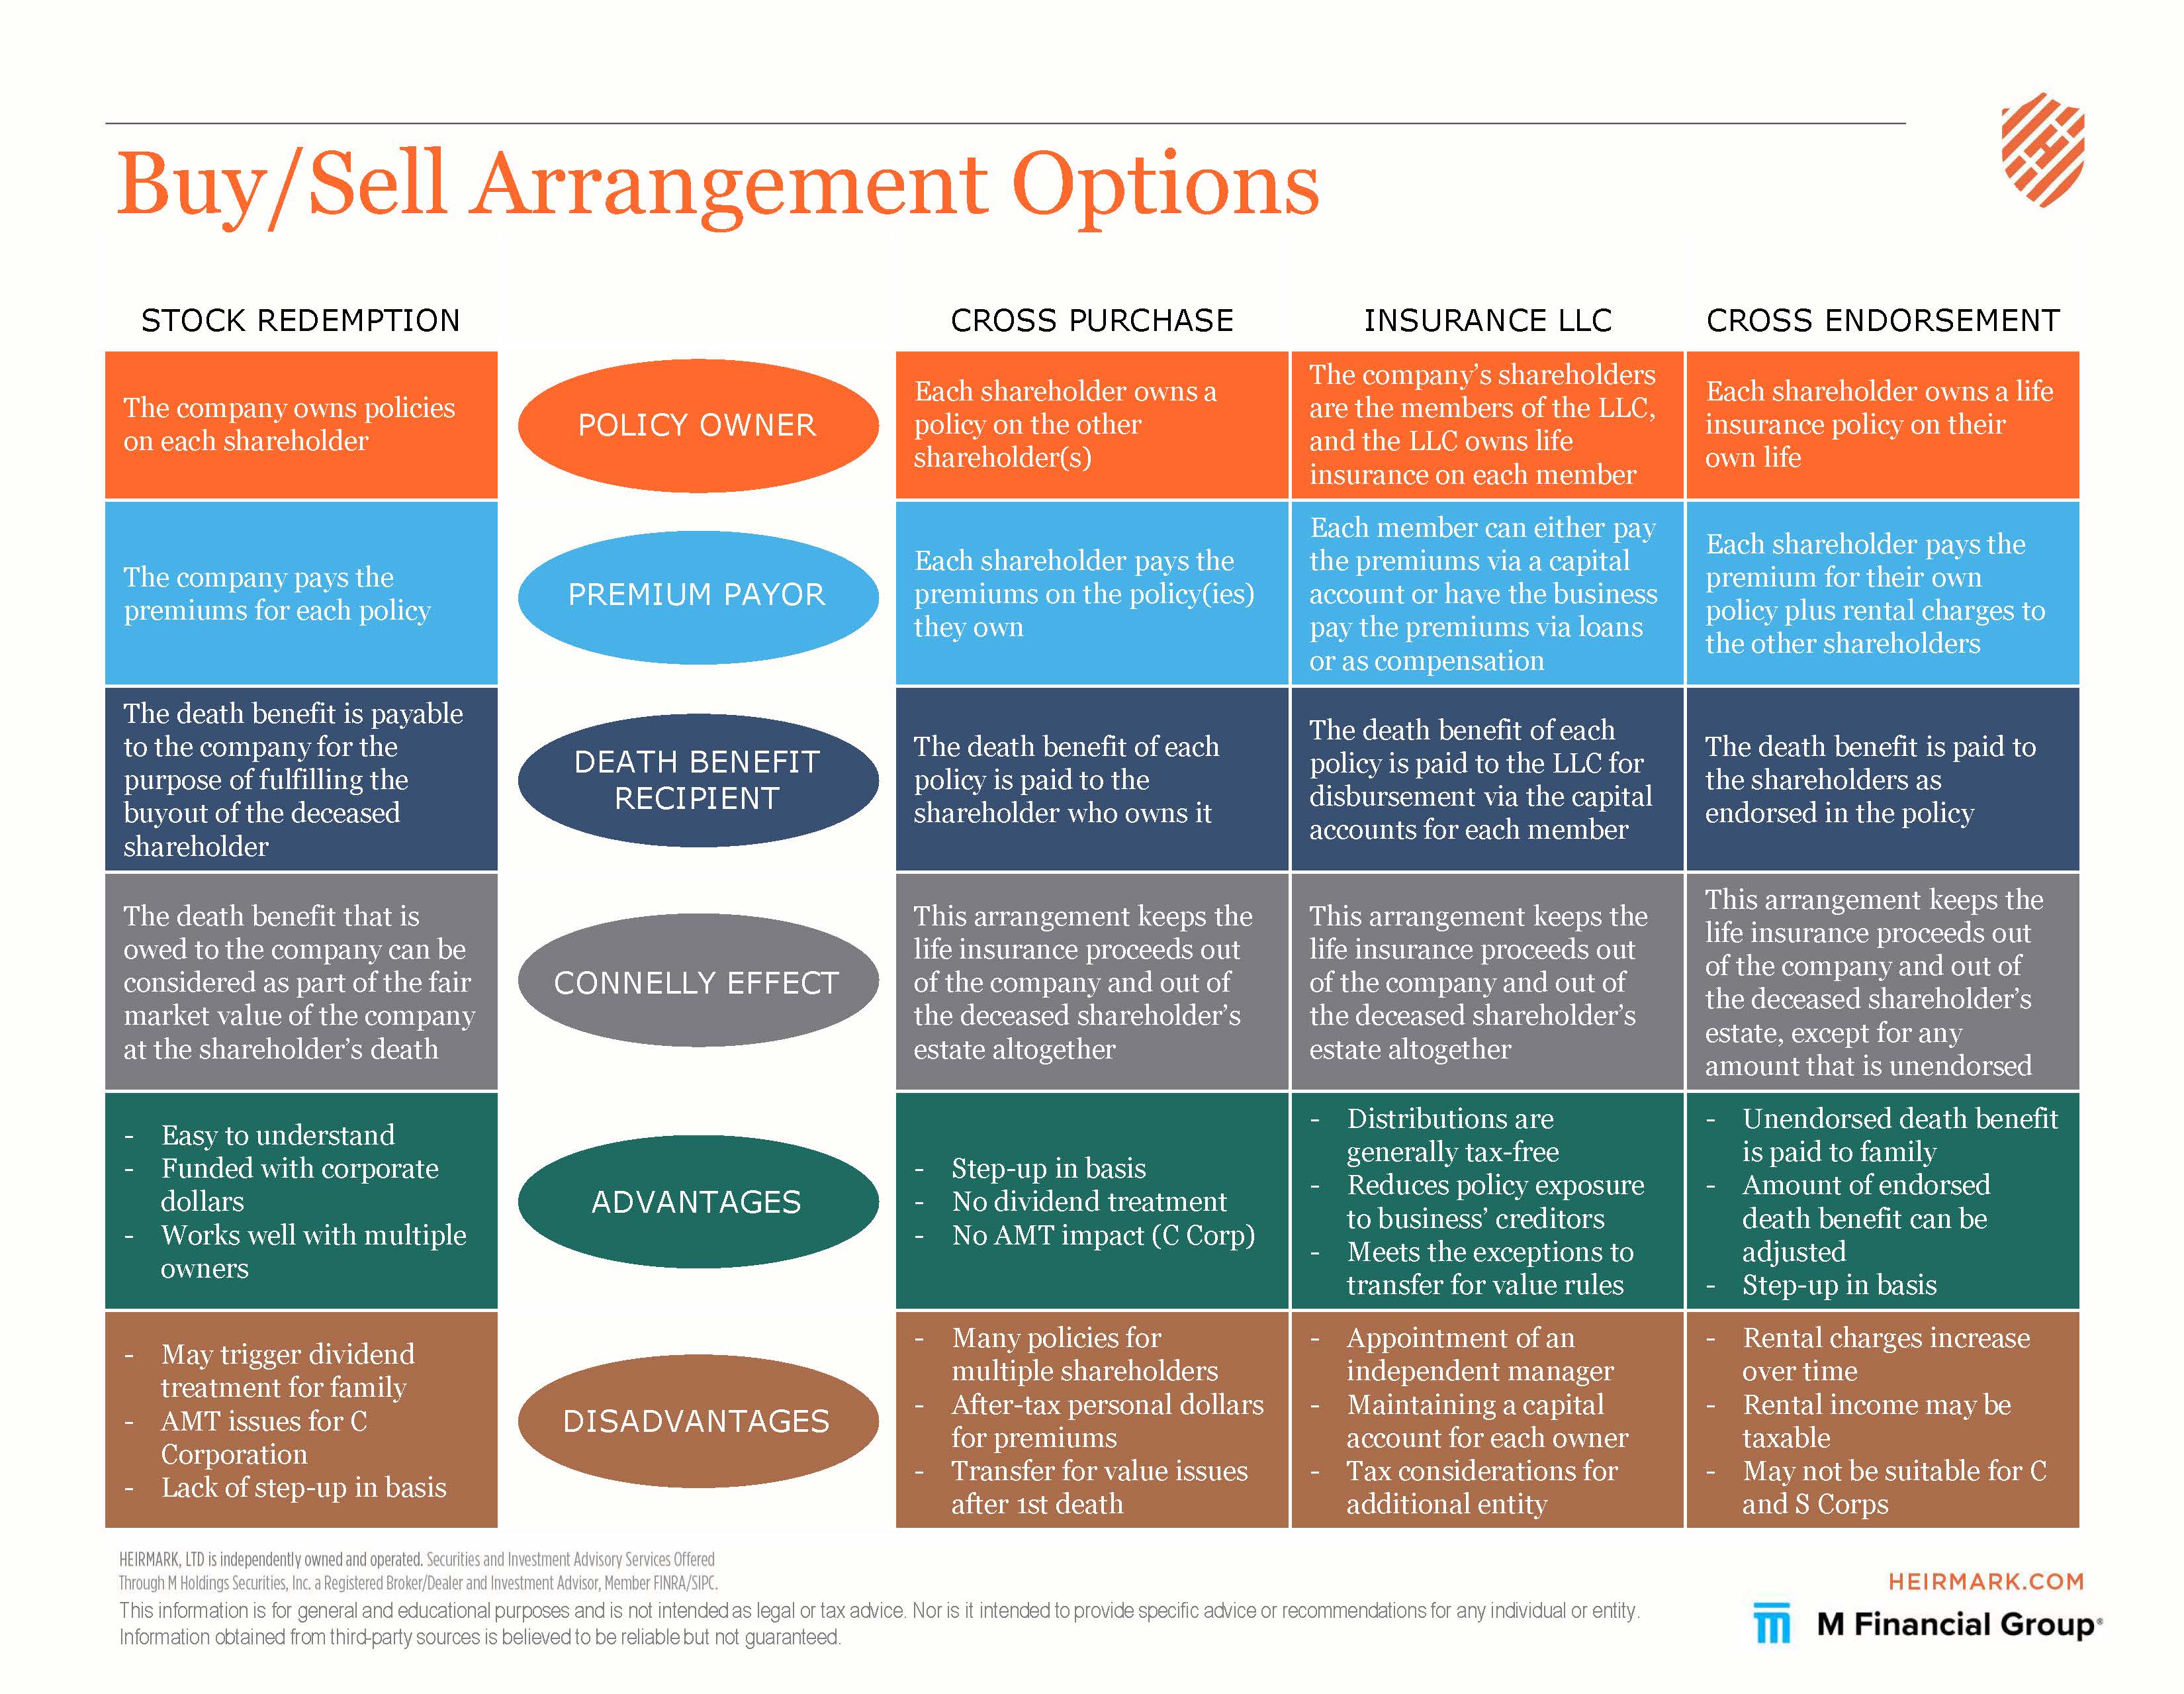
Future interpretation of the language used by the Supreme Court might have a narrow or broad effect to the landscape of buy/sell life insurance held within a company; time will tell. In the short-term, family-owned companies with shareholders who will incur estate taxes and might have considered stock redemption for their buy/sell arrangements in the past, are exploring different arrangements in the wake of the Connelly Supreme Court decision. Outlined in the graphic below is a comparison of stock redemption and three alternative buy/sell arrangements to consider.
Each arrangement has its pros and cons, so there is no one size fits all solution. When considering the preferred buy/sell arrangement for a family-owned business, there are extenuating circumstances that can affect which arrangement will work for each company. For instance, family dynamics can play a huge part in how to structure the agreement. Other factors include the age of the shareholders (to determine an approximation of how far back the Connelly decision will be in the rearview at life expectancy), if their succession plan includes passing the company down within the family, and the shareholders’ sophistication for planning techniques that might require routine maintenance.
We will continue to monitor the ramifications of the Supreme Court ruling in Connelly v. U.S. and provide any updated details as we are made aware of them. Contact us with any questions or opportunities to help you or your clients achieve identified goals. This is what we enjoy doing for only a select number of families, businesses, and charitable institutions each year, and we look forward to hearing from you.