By Raymond Nash
Life Insurance for Generations X, Y, Z
Retiring in a Sandwich
The Great Wealth Transfer is on the horizon with over $100 trillion expected to be passed from Baby Boomers to Generations X, Y, and Z by 2048. This multi-year event will prompt a lot of estate planning in its wake with each generation having its own approach towards inheriting wealth and structuring their financial planning. With these thoughts in mind, it can be advantageous to get started with financial planning now for the future of these generations.
Generation X is generally considered to be those who are currently 45-60 years old. This age demographic typically consists of empty nesters who are looking forward to retirement. However, wealthy Baby Boomers are delaying the passage of money to their heirs, prohibiting Gen X from investing in their future. According to a recent study, 80% of Gen Xers with 401(k)’s don’t think they’ll be able to afford their current standard of living during retirement.
A big contributor to the lack of retirement preparation is that Gen X is the “Sandwich Generation.” It is estimated that 26% of adults in the U.S. are taking care of their elderly parents and their children at the same time; sandwiched between the two generations. The 2008 recession hit some Baby Boomers hard, and their Gen X children might have to supplement the shortfall by paying for some of their parents’ monthly expenses in later years. Meanwhile, Gen X parents of adult children are funding their children’s lives more frequently than ever. A recent study shows that 63% of parents with adult children contribute to their everyday expenses.
Longevity is another consideration. It’s estimated that the global population of people over the age of 100 will swell to 3.7 million by 2050. Considering retirement age is 67 for Gen X, that’s a potential 33+ years of retirement income planning. Likewise, Baby Boomer parents might reach age 100, delaying an inheritance when their Gen X children should be entering retirement. This might complicate the retirement decision for Gen Xr’s if they do not have a comprehensive strategy.
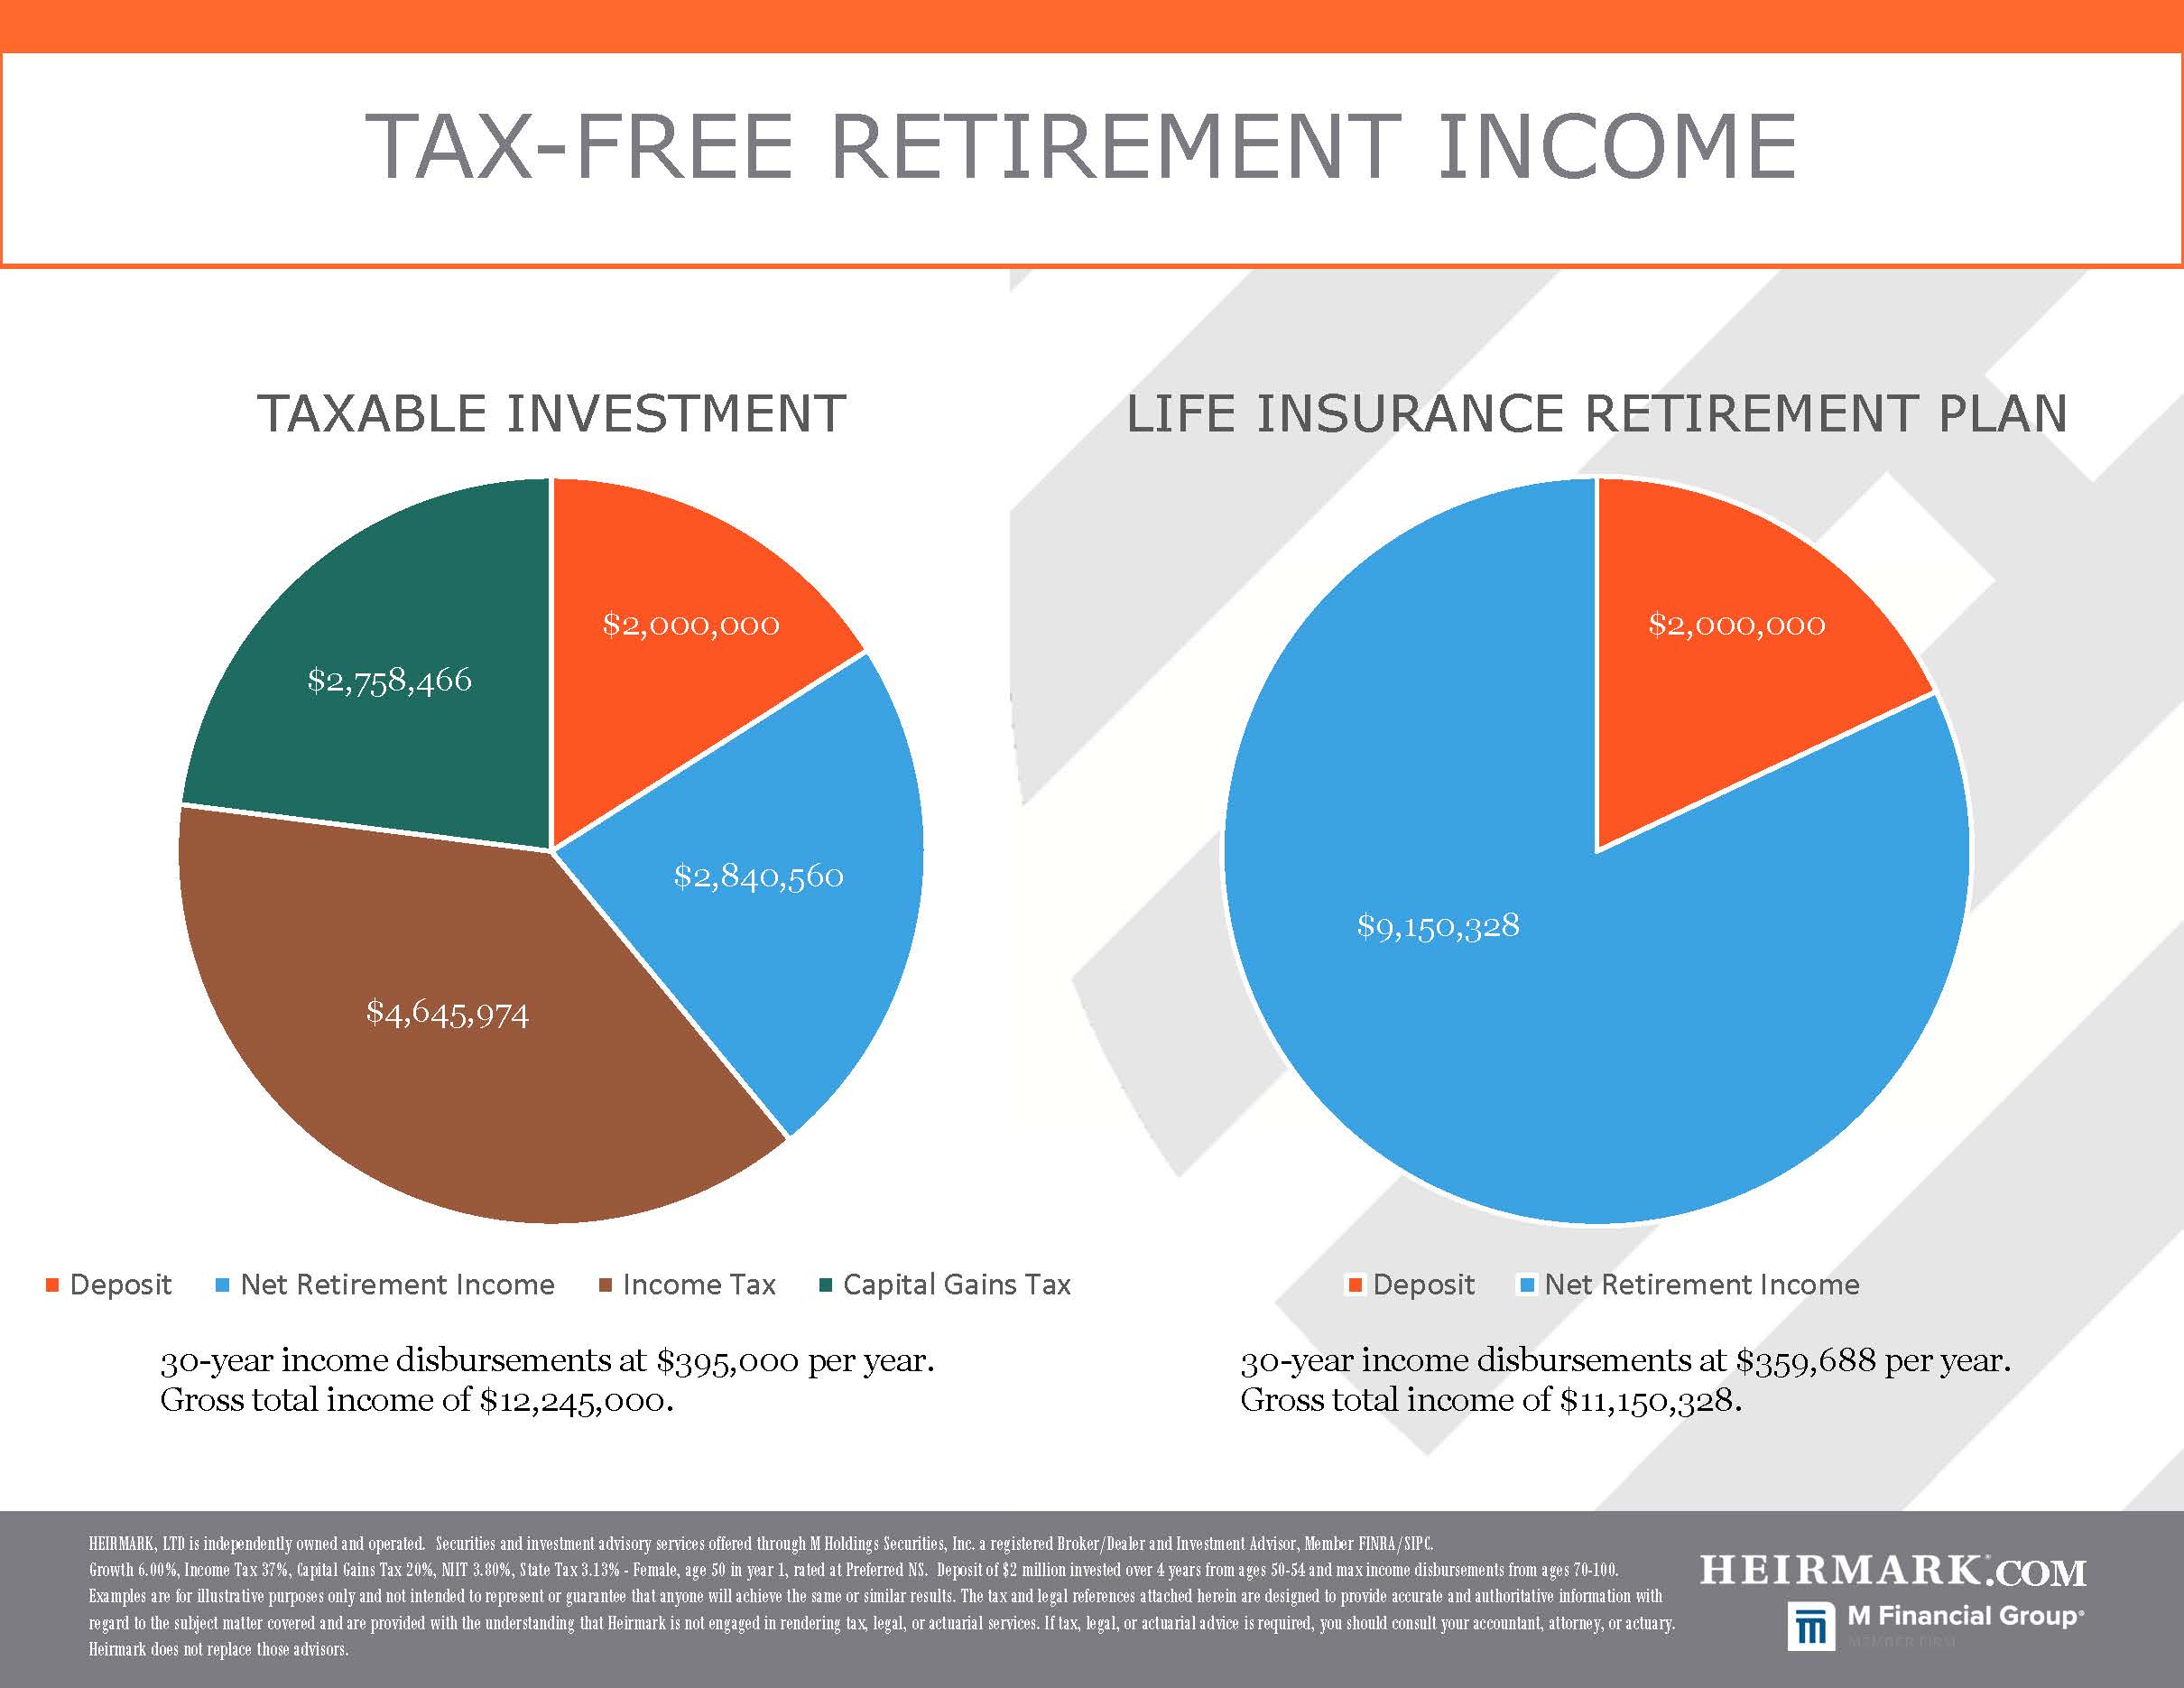
Retirement planning for Gen X should be tiered and flexible. A financial portfolio that focuses on diversification is key, including products that have guaranteed income streams and products with market exposure to hedge against inflation. In addition to other qualified and non-qualified plans, Life Insurance Retirement Plans (LIRPs) can create additional retirement income and Long-Term Care (LTC) coverage can lessen the expense of home healthcare or facility expenses. It’s not just about having insurance; it’s about having a strategy.
Contact us with any questions or opportunities to help you or your clients achieve identified goals. This is what we enjoy doing for only a select number of families, businesses, and charitable institutions each year, and we look forward to hearing from you.