By Raymond Nash
Life Insurance for Generations X, Y, Z
The Internet Is Not an Expert
The Great Wealth Transfer is on the horizon with over $100 trillion expected to be passed from Baby Boomers to Generations X, Y, and Z by 2048. This multi-year event will prompt a lot of financial planning in its wake with each generation having its own approach towards inheriting wealth and structuring their plan. With these thoughts in mind, it can be advantageous to start planning now for the future of these generations.
Generation Z, generally considered those aged 13-28, is often overlooked when it comes to estate planning. Younger generations rely heavily on technology, instead of people, to make decisions. While convenient, the internet contains a lot of misinformation and even worse, disinformation. Interestingly, data shows that Gen Z is open to being mentored when making big decisions. More often than the two generations before them, Gen Zers are seeking support and advice on their path to becoming competent, confident adults. It appeals to them to have a financial advisor as a consultant or collaborator to provide current, objective advice.
Gen Zers who come from generational wealth are poised to inherit, so early education and consultation, even before they are the family’s decision-makers, can go a long way in establishing a rapport to ultimately become the person they contact when creating a full financial plan for their inheritance. They want transparency, clear instruction, and are charitably minded, preferring a financial plan that focuses on their voice and their values. Creating a plan that is hyper-personalized for them is key, since they are used to their favorite social media algorithm delivering their preferred content directly to them.
Many Gen Zers feel uncertain and anxious about the future. They want clear instruction with short-term goals and to feel rewarded for completing each step. Having a plan negates the uncertainty of wondering, “What is the next step?” and creates a sense of accomplishment. They like the idea of aligning their financial goals with their values and investing to make a difference, using their money to create a future they want to live in. In addition to growing their wealth through investments, they need stability and guarantees for a risk-heavy future.
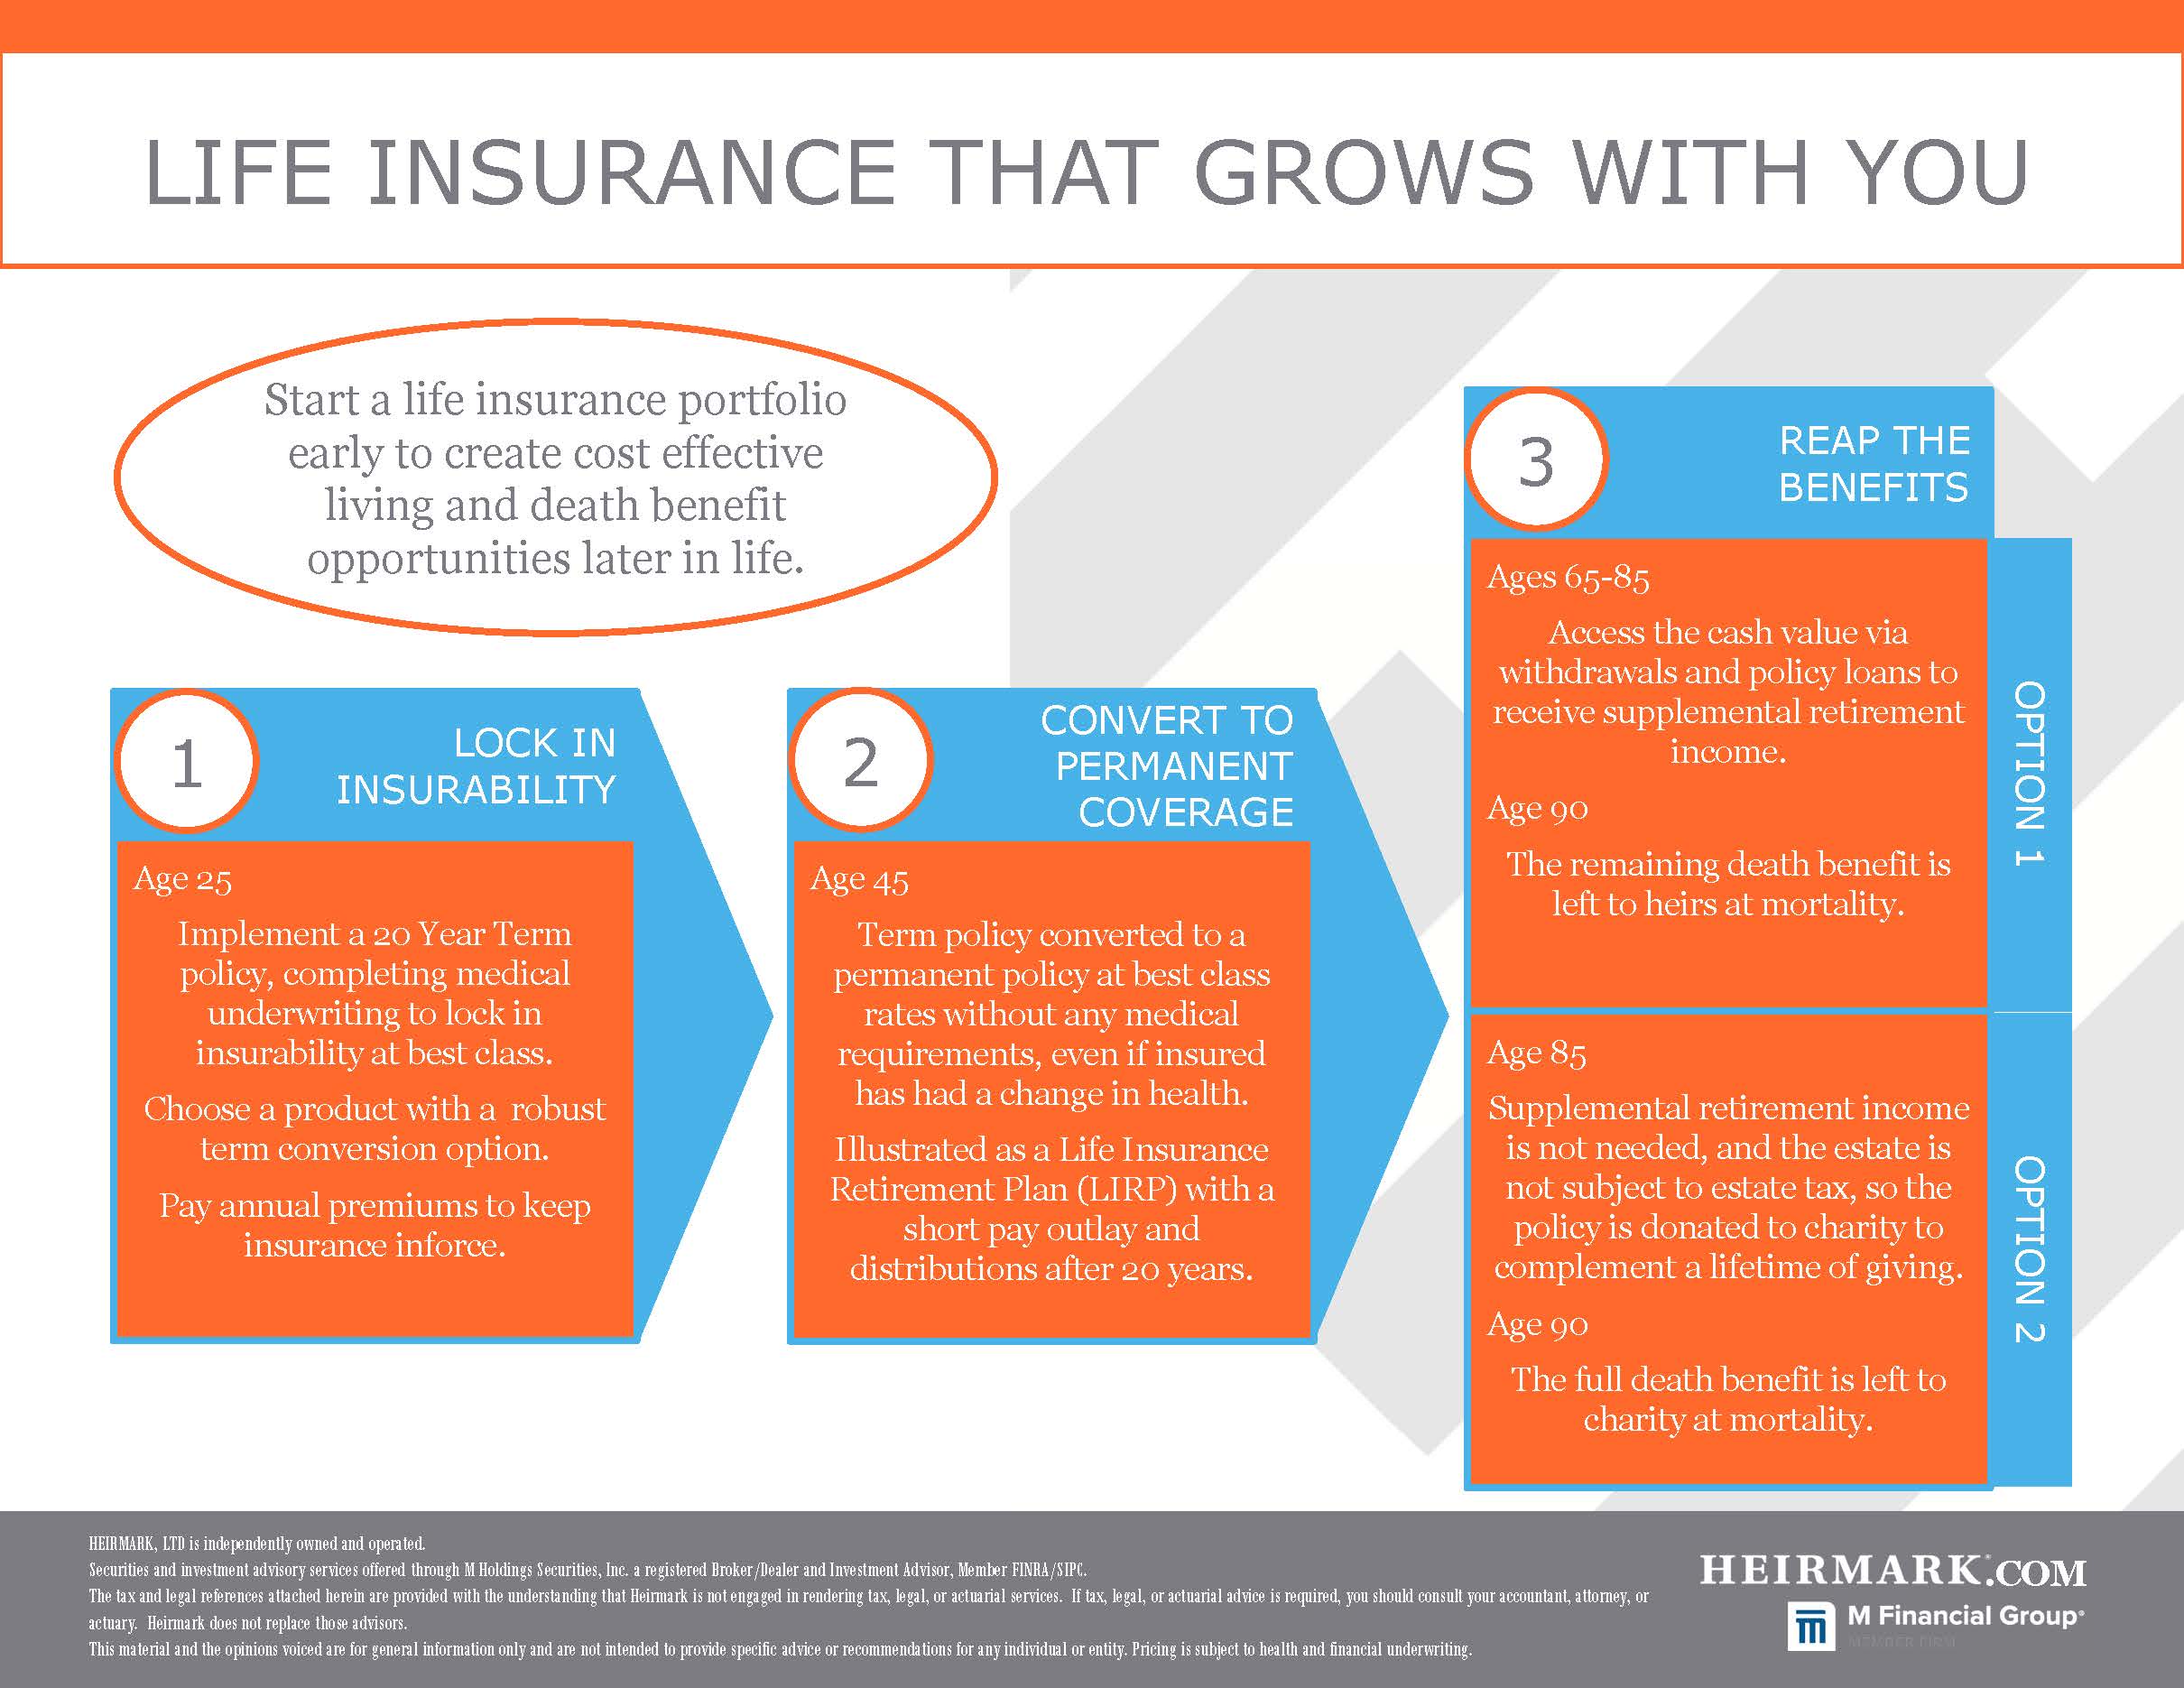
As each generation progresses, longevity becomes more of a key issue; affecting how a financial plan is built and how risk inside the portfolio is measured. Inflation-adjusted products, such as annuities, permanent life insurance, private credit, infrastructure, and real estate are good considerations for preserving and growing wealth. Starting early can be cost effective, especially when considering life insurance. Locking in insurability at a young age with a term policy reserves the insured the right to convert that policy to permanent insurance within the conversion window, even after a decline in health. The permanent policy can then accumulate cash value to create opportunities for living benefits. Ultimately, the living benefits can be used and the death benefit left to heirs, or the policy can be donated to charity (among other exit strategies) if the living and death benefits are no longer needed by the insured or their family.
Contact us with any questions or opportunities to help you or your clients achieve identified goals. This is what we enjoy doing for only a select number of families, businesses, and charitable institutions each year, and we look forward to hearing from you.