By Raymond Nash
Danger Zones
Underperforming Policy
During the month of May, we are taking time to explore potential danger zones when considering existing life insurance policies. Policy implementation is just the beginning of the relationship between a client and life insurance agent. Ongoing service of a policy is an important part of the role to make sure that the policy portfolio continues to fill the needs of the client.
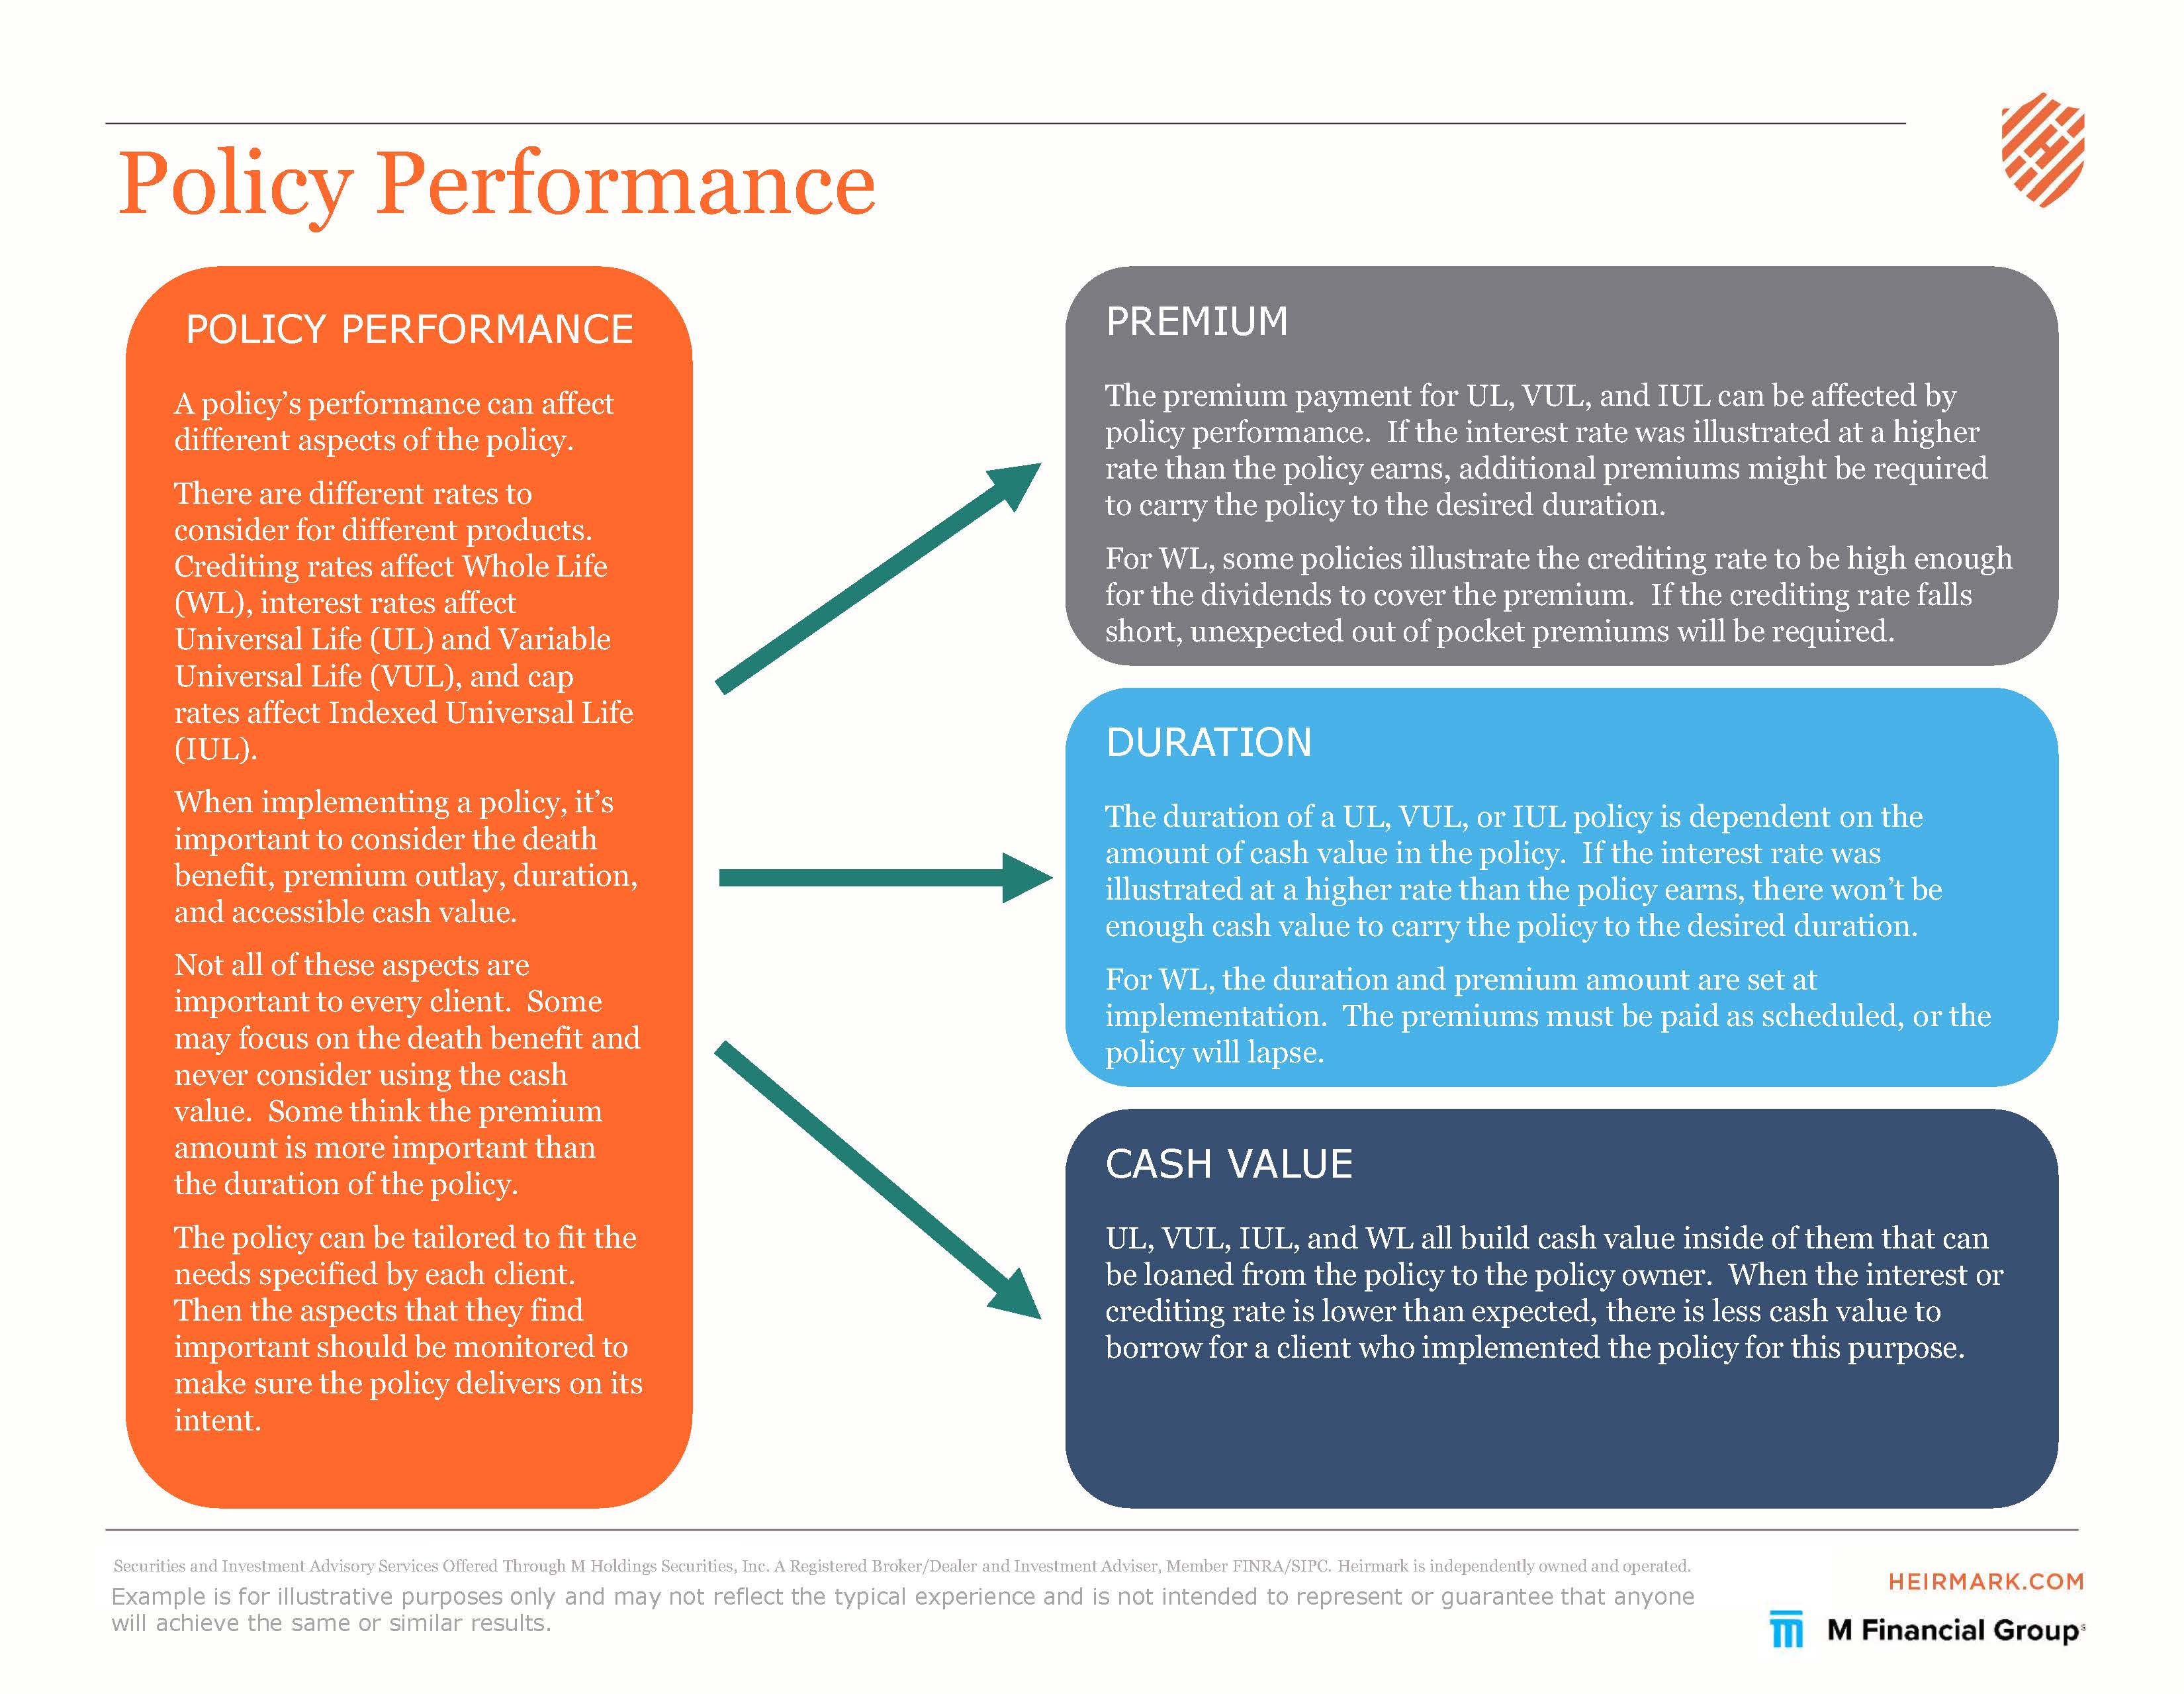
As an example, some life insurance agents inflate the illustrated interest rate for policies at implementation. We’ve seen Variable Universal Life (VUL) policies that were illustrated at 8%-14% and are currently earning 5%. When illustrating future performance, we are conservative in our assumptions to set more realistic expectations for the non-guaranteed aspects of the policy.
Likewise, it’s wise to be aware of the current (versus expected) dividend rate and crediting rate for Whole Life (WL) policies and the cap rate for Indexed Universal Life (IUL) policies. These rates are not guaranteed and subject to performance and/or the insurance carrier’s discretion.
The best safeguard for any policy that relies on a non-guaranteed interest/crediting/cap rate is to request an in-force ledger on an annual basis. For instance, we’ve seen the cap rate decrease substantially in the past 10 years, so older IUL policies should be audited. Performing regular policy audits is a good way to monitor policy performance and adjust a portfolio as needed.
Contact us with any questions or opportunities to help you or your clients achieve their goals. This is what we enjoy doing for only a select number of families, businesses, and charitable institutions each year, and we look forward to hearing from you.
This material and the opinions voiced are for general information only and are not intended to provide specific advice or recommendations for any individual or entity. To determine what is appropriate for you, please contact your Heirmark professional.